Brazil's 2027 Tax Changes for Property Owners
Brazil's new consumption tax starts in earnest on January 1, 2027, with special rules for property sales, rentals and short stays. Most individual owners will stay outside it. Here is how to tell which side you are on, and what else changed for owners in 2026.
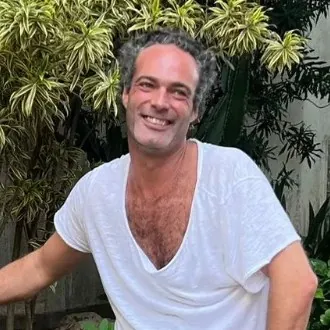
Photo: the infinity pool of a duplex penthouse in Vidigal that Art de Vivre has for sale, looking over Leblon and Ipanema.
- From January 2027 the new federal tax, the CBS, replaces PIS and Cofins. The state and city tax, the IBS, phases in from 2029 and is complete in 2033.
- An individual pays it on rentals only if, in the previous year, rental income passed R$240,000 (indexed) and covered more than three properties. Short stays count toward both tests.
- For owners inside the tax, short stays of up to 90 days are taxed like hotel services, with a 40% rate cut; long leases get a 70% cut.
- The 2026 income tax law withholds 10% on dividends paid abroad, which reaches owners who hold Rio property through a Brazilian company.
- For non-resident individuals, rent is still taxed at 15% at source through their procurador, and capital gains at 15% to 22.5%.
- Reading time
- 24 min
- Length
- 5,430 words
- Chapters
- 13
- Published
- October 16, 2026
For years, Brazil's tax reform was something owners read about and filed for later. In 2027 it arrives. On January 1, the new federal consumption tax, the CBS, is charged in full and two old federal taxes, PIS and Cofins, disappear. The law that regulates it, Lei Complementar 214 of 2025, has a whole chapter on property: sales, long leases, short stays, brokerage and construction. And a separate income tax law, in force since January 2026, changed how dividends are taxed, including dividends paid to owners abroad.
The first thing to know is reassuring. Most individual owners, Brazilian or foreign, who rent out one, two or three homes will not pay the new tax at all. The law draws a line based on how much rental income you earn and how many properties you rent, and it applies only to owners above that line. The second thing to know is that the line now counts short stays, and that owners who hold property through a company, or who own several homes, should look at their numbers now, because 2026 is the year that decides who pays in 2027.
This guide sets out the rules as the law states them, article by article, with what is settled and what is still pending, and it is written for owners of homes in Rio. It is general information from a brokerage and rental manager, not tax advice. Every owner's position depends on their residence, their structure and their other income, and we recommend reviewing yours with a Brazilian accountant or tax lawyer; we can introduce you to the ones we work with.
What changes in 2027
Brazil's consumption tax reform was written into the Constitution by Constitutional Amendment 132 of December 2023 and regulated by Lei Complementar 214 of January 2025, which a second law, Lei Complementar 227 of January 2026, amended and completed. It replaces five old taxes with two new ones and a third, smaller one.
- The CBS, the Contribuição sobre Bens e Serviços, is federal. It replaces PIS and Cofins and is charged in full from January 1, 2027.
- The IBS, the Imposto sobre Bens e Serviços, is shared by states and cities. It replaces the state ICMS and the city ISS, phasing in from 2029 to 2032 and in full from 2033.
- The Imposto Seletivo is an excise tax on goods considered harmful, such as tobacco and alcohol, from 2027. It does not touch property.
Together, the CBS and the IBS work like a value-added tax: each business in a chain pays tax on its sales and takes a credit for the tax on its purchases. The combined standard rate has not been fixed. The most recent official estimate, used by the IBS management committee in July 2026 to plan its budget, was 27.91%, with the CBS at 9.21% and the IBS at 18.70%, and the committee stated that this was not the final rate.
The property chapter
Property gets its own regime in the law, with lower rates than the standard. Sales of property are taxed at the standard rate less 50%. Long leases, onerous cessions and arrendamentos are taxed at the standard rate less 70%. Short stays of up to 90 days are taxed under the hotel rules, with a 40% cut. On top of the cuts, the law gives fixed deductions, the redutores, for residential sales and rentals. All of this applies only to owners who are taxpayers under the new system, and for individuals that depends on the tests in the next chapters.
Income tax changes too
Separately, Lei 15.270 of November 2025 changed the income tax from January 2026: a larger exemption for lower incomes, a minimum tax on high incomes, and, for the first time since 1995, a tax on dividends, including a 10% withholding on every dividend paid abroad. That law matters to owners who hold Rio property through a Brazilian company, and we cover it below.
The transition, year by year
The reform switches on over seven years. The constitutional amendment sets the calendar, and the regulating law adds the details.
| Ano | What happens |
|---|---|
| 2026 | Test year. CBS at 0.9% and IBS at 0.1%, offset against PIS and Cofins. Taxpayers who file correctly pay nothing. |
| 2027 | CBS charged in full; PIS and Cofins end; IPI goes to zero for most goods; the Imposto Seletivo starts. IBS at a token 0.1%. |
| 2028 | As 2027. |
| 2029 to 2032 | IBS phases in while ICMS and ISS fall to 90%, 80%, 70% and 60% of their rates. |
| 2033 | ICMS and ISS end. The new system applies in full. |
The 2027 rate is still being set
The CBS rate for 2027 had not been published in October 2026. Under the schedule agreed between the government, Congress and the federal audit court, the TCU, the Receita Federal sent its calculation model to the TCU in September, the TCU has until October 30, 2026 to validate it, and the Senate must set the rate by resolution by December 15, 2026. If the Senate does not act, the TCU's figure applies. In 2027 and 2028 the CBS rate is the reference rate less 0.1 percentage point, because the IBS is charged at 0.1% in those years. The 2027 budget bill, sent to Congress at the end of August 2026, forecast R$636 billion of CBS revenue but gave no rate.
The law also has a ceiling. If a review in 2030 finds that the combined rates for 2033 would be above 26.5%, the government must send Congress a bill to bring them down.
Why 2026 already matters
The tests that decide whether an individual owner is a taxpayer look at the previous calendar year. That means your rents and sales in 2026 decide whether you pay the CBS on property in 2027. The 2026 test year itself costs taxpayers nothing if they file, but the numbers you earn in it count. Individuals who do become taxpayers will register for a CNPJ, a business tax number, and issue electronic invoices from January 1, 2027, after a decree in July 2026 postponed that step from 2026.
Who pays among individual owners
Companies that buy, sell, build or rent property are taxpayers under the new system as a matter of course. Individuals are not, unless they cross one of the lines in article 251 of LC 214. The law sets three tests, each looking at the previous calendar year.
- Rentals. An individual is a taxpayer on leases if, in the previous year, total income from leases, onerous cessions and arrendamentos of property exceeded R$240,000, e those operations involved more than three distinct properties. Both conditions must be met.
- Sales. An individual is a taxpayer on sales if, in the previous year, they sold or assigned rights over more than three distinct properties that they had owned for less than five years. For inherited or donated property, the five years run from when the deceased or the donor acquired it.
- Self-built property. An individual is a taxpayer if, in the previous year, they sold more than one property that they themselves had built within the five years before the sale.
The R$240,000 figure is indexed to inflation, the IPCA, monthly from the date the law was published in January 2025, so it is already somewhat higher; the updated figure is to be published jointly by the Receita Federal and the IBS committee. The law also has same-year triggers: an individual becomes a taxpayer within the year if their rents exceed the limit by more than 20%, or once they sell beyond the limits for sales. The CBS regulation reads the 20% rental trigger as still requiring more than three properties; the law's own wording is silent on the count, and commentators disagree.
Short stays count
Lei Complementar 227 of 2026 added an important sentence: income from short stays counts toward the R$240,000 limit and the three-property test, and an individual who meets them is a taxpayer on short stays too. Before that change, it was unclear whether short-stay income counted. Now it does. The regulation counts properties, not contracts, and treats a co-owned share as a distinct property.
What this means in practice
An owner with one, two or three homes in Rio, however much they earn from them, does not meet the rental test, because both conditions must be met. An owner with four or more homes rented out, earning more than R$240,000 a year in total, does. An owner who sells their Rio apartment after ten years is not a taxpayer on that sale; an owner who buys and sells several apartments within a few years may be.
- One to three homes rented, any income
- Four homes, R$200,000 of rent in the previous year
- Selling a home owned for more than five years
- Four or more homes and more than R$240,000 (indexed) of rent
- More than three sales in a year of homes owned under five years
- A company that owns and rents property
Owners who live abroad
The law does not say how these tests apply to individuals resident abroad. Its text speaks of any individual, and it names only one category of individual who is never a taxpayer, the nanoempreendedor, a very small self-employed worker. No provision excludes residents abroad, and no source we found confirms how the Receita will treat them. Until that is clarified, a non-resident owner near the thresholds should assume the same tests apply and take advice.
Long-term rentals under the new tax
For an owner who is a taxpayer, a residential lease is taxed at the standard rate less 70%. The tax arises on each rent payment, and the base excludes taxes and fees on the property, such as IPTU, and condominium charges paid by the tenant. On top of the rate cut, a fixed deduction, the redutor social, takes R$600 a month per residential property off the base, up to the amount of the rent, indexed to inflation.
What does that look like? The Ministry of Finance, in a note in January 2026, said that a traditional residential rental by a taxpayer pays an effective consumption tax of about 8% once the system is fully in place, plus income tax. A guide by the law firm Levy Salomão gave a simpler illustration for 2027 and 2028: with the CBS at around 10% and the 70% cut, a long lease pays about 3%, with credits allowed for the tax on related costs. These are illustrations, not official rates, and the 2027 rate will be set in December.
The R$600 deduction
The redutor social is designed to protect smaller residential rents. On a rent of R$3,000 a month, R$600 of it is outside the base, so the tax is charged on R$2,400. On a rent of R$20,000, the deduction makes much less difference. Lei Complementar 227 clarified that the R$600 is per month.
Leases signed before 2025
The law offers a transition option for leases signed before LC 214 was published on January 16, 2025. An owner can choose to pay 3.65% of gross receipts on those leases, with no credits and no redutor social, for the original term of a residential lease or until December 31, 2028, whichever comes first. Non-residential leases had to be registered by the end of 2025 to qualify. For a taxpayer-landlord with older leases, the choice between the transition rate and the new regime is worth running through with an accountant.
For most owners, nothing changes
For an individual owner below the thresholds, a long lease is taxed exactly as before: income tax on the rent, and nothing more. Rents in Rio rose 14.80% in the 12 months to September 2026, according to FipeZap, and the average gross yield for new leases was 6.30%, so long leases remain a solid option. Our comparison of short stays and long leases sets out the numbers, and our long-term rentals page shows the homes we let by the year.
Short stays and the hotel rules
Article 253 of LC 214 is the one short-stay owners ask about. It says that the lease or cession of a residential property, by a taxpayer under the regular regime, for a period of no more than 90 consecutive days, is taxed under the same rules as hotel services. The hotel chapter, article 278, includes a furnished residential property, even one not used exclusively by guests, in its definition of hotel services. So a furnished apartment rented by the night through Airbnb or Booking.com, by an owner inside the tax, is treated like a hotel room.
The hotel regime cuts the standard rate by 40%, less than the 70% cut for long leases. The Ministry of Finance's January note said that short stays get a smaller benefit than long leases. Levy Salomão's illustration, at a 28% standard rate, gives 16.8% on a short stay once the system is in place. At the 2027 and 2028 CBS rate alone, the charge would be a fraction of that, because the IBS is still at 0.1%.
Who the hotel rules apply to
The key word is taxpayer. Since LC 227, an individual is a taxpayer on short stays if they meet the rental tests in article 251: more than R$240,000 of rental income, short stays included, and more than three properties, in the previous year, or the same-year 20% trigger. An owner with one or two apartments on Airbnb is not a taxpayer, however busy the calendar. Whether the R$600 monthly deduction applies to short stays taxed under the hotel rules is not stated in the law, and was still open in October 2026.
The courts and the tax law
In May 2026 Brazil's Superior Court of Justice described short stays through platforms as atypical contracts, neither a residential lease nor hotel lodging, when it ruled that they need the approval of two-thirds of the owners in a residential condominium. The tax law, meanwhile, taxes them like hotels. Both can be true at once, because one is about the building's rules and the other about tax. The court's question is now pending as a repetitive appeal, Tema 1.443, which will set a binding rule. Our guide to short stays and condominium rules explains the ruling.
For an owner deciding between short stays and a long lease, the tax difference matters only above the thresholds. Below them, the choice is about income, effort and how often you want to use the home yourself. Our guide to what a Rio short stay earns and our guide to management costs cover that side.
Airbnb, Booking.com and the platforms
The reform gives digital platforms a central role. Under article 22 of LC 214, a platform that controls at least one essential element of a transaction, such as charging, payment, the terms or delivery, is responsible for the tax on the operations it intermediates in certain cases. Pure payment processors and advertising sites are excluded. Platforms based abroad must register in Brazil; if one does not, the bank that handles the foreign exchange withholds the tax on the remittance.
When the platform pays
If the supplier, in our case the owner, lives abroad, the platform is liable for the tax jointly with the guest, in place of the owner. If the owner lives in Brazil, the platform is jointly liable only when information is missing or when an owner who is a taxpayer fails to issue an electronic invoice. Whether the rule for owners abroad reaches non-residents who are below the thresholds, and so not taxpayers at all, is one of the points still open.
Reporting
Whatever the tax position, platforms must report every operation they intermediate to the Receita Federal and the IBS committee and identify the supplier, even one who is not a taxpayer. In other words, platforms will report each booking to the Receita Federal. For owners who already declare their rental income, nothing changes.
A new option for hosts
LC 227 added an option: with the host's consent, a platform may act as the substitute taxpayer and issue the invoices for the host, using the reference rates. The host remains liable for any difference. How each platform will implement this, and whether they will offer it to hosts in Brazil in 2027, had not been announced in October 2026.
For the homes we manage, our owner statements already record every booking, every payment and every cost, by channel, which is what an accountant needs to check where an owner stands.
Split payment
One of the reform's ideas is split payment: when a buyer pays by card, transfer or Pix, the payment system separates the tax and sends it straight to the government, so the seller never holds it. The law, in article 31 of LC 214, sets the mechanism but no start date.
In practice, it will start slowly. According to the operating manual published by the Receita and the IBS committee, split payment in 2027 is optional and limited to payments between businesses, released gradually through the year. Sales to final consumers, card payments and the smallest businesses are left out at launch. The Receita has said the tool will not be fully running in January 2027, and its target of making business-to-business split payment mandatory in 2028 had not been written into any rule by October 2026.
What it means for owners
For a landlord, a rent paid by an individual tenant, or a guest's card payment for a short stay, falls outside the first phase. In 2027 there will be no automatic split on those payments. A company tenant could opt in. Owners who are taxpayers will still owe the CBS on each rent payment, and will pay it through their own filings, not through the payment system.
Split payment matters more over time. As it reaches card payments and consumer transactions, the tax on short stays will increasingly be collected at the moment the guest pays, either by the platform or by the payment system. That is one more reason for owners near the thresholds to keep clean records from 2026 onward.
For the homes we manage
Payments for stays in the homes we manage reach the owner through the channel the guest booked on, or through our own direct booking system, and every payment is recorded on the owner's statement. When the consumer phase of split payment arrives, the channels will apply it; our statements will show the tax separated where it applies. Our guide to getting paid when you live abroad describes the money path today.
Selling a property
When an individual sells their own home, or a single investment apartment, the sale is outside the CBS and IBS, because the sales tests apply only to people who sell more than three properties held under five years in a year, or more than one self-built property. For the ordinary owner, the tax on a sale is the income tax on the capital gain, which the reform does not change.
The capital gains tax
For residents of Brazil, capital gains are taxed at progressive rates: 15% on the part of the gain up to R$5 million, 17.5% from R$5 million to R$10 million, 20% from R$10 million to R$30 million, and 22.5% above. Non-residents are taxed on gains under the same rules as residents, with a 25% rate for residents of jurisdictions Brazil classes as tax-favoured. When the seller lives abroad, the buyer, or the buyer's procurador if the buyer also lives abroad, withholds the tax. Residents have some exemptions, such as reinvesting the proceeds in another home within a set period; whether non-residents can use them is still unclear. Our capital gains guide covers the calculation, and our guide to selling as a foreign owner walks through the sale.
For sellers inside the CBS
For companies and individuals who are taxpayers, a sale is taxed at the standard rate less 50%. Two deductions reduce the base. The redutor de ajuste, which every property of a taxpayer carries from January 1, 2027, is broadly the cost of the property: for a property held on December 31, 2026, its acquisition value updated by inflation, or, at the owner's choice, the official reference value the tax authorities will publish for every property. ITBI and laudêmio paid on the purchase are added to it. The redutor social takes a further R$100,000 off the sale of each new residential unit, once per property.
In effect, the tax falls mainly on the gain and on new building, not on the full price. For developers and active traders this is a real change. For most of our clients, who buy a home to keep, it is background.
Keep your purchase records
Whichever side of the line you are on, the documents from your purchase matter more than ever: the deed, the ITBI receipt, any laudêmio receipt, and receipts for renovations. They set your cost for the capital gains tax and, for taxpayers, the redutor de ajuste.
The 2026 income tax law
The second big change for owners is already in force. Lei 15.270 of November 26, 2025, changed Brazil's income tax from January 1, 2026, in three ways.
A larger exemption
For residents of Brazil, monthly income up to R$5,000 is now effectively exempt, through a reduction of up to R$312.89 that brings the tax to zero, with a sliding reduction up to R$7,350 a month. On an annual basis, income up to R$60,000 is exempt, sliding to R$88,200. For a resident whose only income is a modest rent, this may mean little or no income tax from 2026. Whether the monthly reduction applies inside the carnê-leão, the monthly payment residents make on rents received from individuals, was a point on which sources differed in October 2026.
A minimum tax on high incomes
Residents with total annual income above R$600,000 now face a minimum tax, rising in a straight line from 0% at R$600,000 to 10% at R$1.2 million and above. The base includes income that was exempt or taxed separately, and income tax already paid is deducted. The law lists what is excluded, and capital gains, other than those on exchange-traded assets, are on the list, so the gain on selling a property does not enter the minimum tax. Rental income is not on the exclusion list, so on our reading rents count toward the R$600,000 test.
A tax on dividends, including dividends paid abroad
For the first time since 1995, Brazil taxes dividends. For residents, 10% is withheld on the total paid in a month when one company pays more than R$50,000 to one person in that month. For shareholders abroad, 10% is withheld on every dividend, whatever the amount. Profits earned up to 2025 and approved by December 31, 2025 are exempt. The Receita Federal confirmed in December 2025 that the 10% applies to all dividends sent abroad, including to tax-favoured jurisdictions, and the law gives foreign shareholders a credit when the company's tax plus the 10% exceeds the nominal corporate rate.
Who the dividend tax affects
The dividend rule matters most to owners who hold Rio property through a Brazilian company, which some foreign buyers chose in the past for flexibility. Rental profits paid out to a shareholder abroad now carry 10% that they did not carry before 2026. Rent received directly by a non-resident individual keeps its own 15% rule, covered in the next chapter. If you own through a company, 2026 and 2027 are a good time to review whether that structure still suits you; our guide to tax for foreign owners in Brazil explains the main structures.
What stays the same for non-residents
For a foreign owner who lives abroad and owns a Rio home in their own name, most of the rules that matter day to day do not change in 2027.
Alugar
Rent from Brazilian property paid to a non-resident individual is taxed at 15%, withheld at source, or 25% if the owner lives in a jurisdiction Brazil classes as tax-favoured. The tax is final: there is no annual return in Brazil for that income. The person who withholds it is the owner's procurador, the legal representative in Brazil, who must withhold even when the tenant is an individual; in practice the tax is paid on the day the rent is received, on a DARF, the federal payment slip, under code 9478. Documented expenses can be deducted first: IPTU and other taxes on the property, the cost of collecting the rent, such as a rental agency's fee, and condominium charges.
This is why we always recommend that a foreign owner who rents out a Rio home has a procurador in Brazil. Our guide to getting paid when you live abroad walks through the money path, from the guest's payment to the owner's account at home, and our guide to running a Rio rental from abroad covers the rest.
The CPF
Every individual who owns property in Brazil subject to public registration, or who carries out property transactions in Brazil, must hold a CPF, the taxpayer number, whether they live in Brazil or abroad, under the Receita's rules of 2024. A CPF can be obtained at a Brazilian consulate abroad.
Ganhos de capital
As above, a non-resident's gain on a sale is taxed under the rules for residents, at 15% to 22.5% depending on the size of the gain, or 25% for tax-favoured jurisdictions, withheld by the buyer or the buyer's procurador. Money that came into Brazil through a registered foreign exchange contract can leave again on a sale, which is why we insist on registering the purchase funds correctly from the start.
Tax at home
Most foreign owners also report their Rio rent and any gain at home, and many countries give a credit for tax paid in Brazil, under a tax treaty or their own rules. Brazil has treaties with some countries and not others; the United States, for example, has none with Brazil, while France, Portugal and Spain do. That is a question for your adviser at home.
ITBI, IPTU and laudêmio in Rio
The city taxes on owning property in Rio are not part of the reform, but two changes touch them, and they belong in any owner's planning.
ITBI, the transfer tax
The buyer pays ITBI, the municipal property transfer tax, before the deed is registered. In the city of Rio the rate is 3%, raised from 2% from January 2018 by city law 6.250 of 2017; we found no later law changing it, though some online calculators still show 2%. The base has been a point of dispute for years: Rio has often charged ITBI on its own valuation rather than the declared price. In August 2026 a Rio court ordered the city to refund ITBI charged on R$350,000 when the declared price was R$305,000, following the Superior Court of Justice's position that the declared price is presumed correct unless the city opens a formal procedure. LC 227 of 2026 then rewrote the national rule: the base is the market value, estimated on technical criteria, and cities must publish their method and let owners contest it. How Rio applies it from 2027 is still to be seen.
IPTU, the annual property tax
Residential property in Rio pays IPTU at 1% of the city's assessed value, which is revised every four years. For 2026 the city corrected the values by inflation and offered a 7% discount for payment in a single installment in February, or payment in ten installments. The 2027 figures had not been announced in October 2026. IPTU is deductible from a non-resident's rent for income tax.
Laudêmio
Much of Rio's coast, from Zona Sul to Barra, sits on terreno de marinha, seashore land that belongs to the federal government. When such a property is sold, the seller pays the laudêmio, 5% of the updated value of the land, not the building, before the transfer. The federal property office counted 55,919 affected units in the city in 2016. Some properties also owe private enfiteuse charges to the city, old families or religious bodies. For a taxpayer under the new system, laudêmio paid on a purchase is added to the redutor de ajuste.
Our guide to the cost of buying property in Rio puts all of these into one budget, with the notary and registry fees.
Rio's own rules on short stays
Alongside the federal reform, the city of Rio has been debating its own rules for short stays. A bill in the city council, PL 372 of 2025 (first filed as PL 107/2025), as first written would have banned short stays of under 90 days through platforms in residential buildings on some Zona Sul beachfront avenues, a ban a 2025 committee report is reported to have dropped, and would require registration with the Ministry of Tourism and the city, permits, annual condominium approval, guest records, the withholding of the city's service tax, ISS, by the platforms, and fines of R$10,000. The council created a special committee on the subject in March 2025. As of October 2026 we found no plenary vote, and the bill is not law.
We are following the bill, and if it moves forward we will write to any owner it could affect and update this guide.
No tourist tax, and no ISS on owners today
Rio has no tourist tax on stays, and no city service tax, ISS, on an individual owner's short-stay rentals today; the city bill would create one, but ISS itself begins to phase out from 2029, when the IBS replaces it.
The courts and condominiums
The question that matters most for apartment owners remains the one in the courts. The Superior Court of Justice ruled in May 2026 that habitual short stays in a residential condominium need the approval of two-thirds of the owners, and in September 2026 it took the question up as a repetitive appeal, Tema 1.443, to set a binding rule: does a residential-use clause alone bar short stays, or must the convention ban them expressly? All such cases in Brazil are suspended until it rules. The federal prosecutors' office gave the opinion, in August 2026, that no approval should be needed unless the convention expressly prohibits them.
For an owner today, the safe course is the one we recommend to buyers: know what your building's convention says, keep good relations with the síndico, and run a short stay the neighbors are glad to have in the building: clear house rules, guests registered with the concierge, and someone in Rio the building can call.
What to do before January
For most owners, the reform asks for very little. For some, a few hours with an accountant this autumn will save time and money in 2027. Here is the list we are giving the owners whose homes we manage.
- Count your properties and your 2026 rent. Add up rental income from long leases and short stays across every property you own in Brazil, including shares in co-owned property. If you are well below R$240,000 or own three or fewer, the CBS rental test does not reach you in 2027.
- If you are near the line, plan. An owner with four or more rented properties and rent close to the limit should look at the numbers with an accountant before December, and keep an eye on the same-year 20% trigger during 2027.
- Check how you hold the property. If a Brazilian company owns your Rio home, the 10% withholding on dividends abroad applies from 2026. Ask whether the structure still makes sense.
- Make sure your procurador is withholding. If you live abroad and receive rent, the 15% should be withheld and paid on each payment. Not sure it is? Ask us and we will go through your statements with you.
- Gather your purchase documents. Deed, ITBI and laudêmio receipts, and renovation invoices set your cost for capital gains, and for taxpayers the redutor de ajuste.
- Read your building's convention. If you rent by the night in a condominium, know what the convention says while the courts decide.
- Watch two dates. The TCU's validation of the CBS rate by October 30, 2026, and the Senate's resolution by December 15, 2026.
How we help
For the homes we manage, we send each owner a monthly statement with every booking, payment, fee and expense, by channel, which is the record an accountant needs for both income tax and the new tests. We work with independent Brazilian accountants and tax lawyers and can introduce you to them. And when the 2027 rate and the open points are settled, we will update this guide and write to our owners.
If you are thinking of buying, our guide to buying property in Rio in 2027 covers prices, rates and neighborhoods, and our foreign buyer's guide covers the steps.
Frequently asked questions
Will I pay the new CBS on rent from my Rio apartment?
Only if you are a taxpayer under the new system. An individual is a taxpayer on rentals if, in the previous year, rental income exceeded R$240,000 (indexed to inflation) and the leases covered more than three distinct properties. Both tests must be met. An owner of one to three rented homes is outside the CBS on rentals.
Does Airbnb income count toward the R$240,000 limit?
Yes. Lei Complementar 227 of 2026 added to article 253 of LC 214 that short stays count toward the R$240,000 limit and the three-property test. An individual who meets both is a taxpayer on short stays too, which are taxed under the hotel rules with a 40% rate cut.
When does the new tax start?
2026 is a test year, with CBS at 0.9% and IBS at 0.1%, waived for taxpayers who file correctly. From January 1, 2027 the CBS is charged in full and PIS and Cofins end. The IBS phases in from 2029 to 2032 and the new system is complete in 2033.
What is the CBS rate in 2027?
It had not been set in October 2026. The TCU must validate the Receita's calculation by October 30, 2026, and the Senate must set the rate by December 15, 2026. The latest official estimate of the combined CBS and IBS standard rate was 27.91%, which the IBS committee said was not final.
How is rent taxed for a foreign owner who lives abroad?
Rent paid to a non-resident individual is taxed at 15% at source, or 25% for residents of tax-favoured jurisdictions. The owner's procurador in Brazil withholds it, even when the tenant is an individual. IPTU, a rental agency's collection fee and condominium charges can be deducted first.
Are dividends paid abroad taxed in Brazil now?
Yes. Lei 15.270 of 2025 withholds 10% on every dividend paid to a shareholder abroad from 2026, whatever the amount. Profits earned up to 2025 and approved by December 31, 2025 are exempt. This affects owners who hold Rio property through a Brazilian company.
Does the tax reform change the capital gains tax on selling a home?
No. An individual selling their own home or a single investment is outside the CBS on that sale. The income tax on the gain is unchanged: 15% up to R$5 million, rising to 22.5% above R$30 million, with 25% for tax-favoured jurisdictions. Non-residents are taxed under the same rates.
What is the ITBI rate in Rio de Janeiro?
City law 6.250 of 2017 raised Rio's ITBI rate to 3% from January 2018, and we found no later change. The buyer pays it before the deed is registered. LC 227 of 2026 requires cities to publish how they estimate the market value used as the base.
Where the facts come from
- Câmara dos Deputados, Constitutional Amendment 132/2023, December 20, 2023
- LC 214/2025, art. 251, individuals as taxpayers (consolidated text), read October 16, 2026
- LC 214/2025, art. 253, short stays under the hotel rules, read October 16, 2026
- LC 214/2025, art. 261, rate reductions for property, read October 16, 2026
- LC 214/2025, art. 260, redutor social on rentals, read October 16, 2026
- LC 214/2025, arts. 257 and 258, redutor de ajuste, read October 16, 2026
- LC 214/2025, art. 278, hotel services include furnished homes, read October 16, 2026
- LC 214/2025, art. 281, hotel rate reduction, read October 16, 2026
- LC 214/2025, art. 22, digital platforms, read October 16, 2026
- LC 214/2025, art. 487, transition for older leases, read October 16, 2026
- LC 214/2025, art. 348, the 2026 test year, read October 16, 2026
- Decreto 12.955/2026, art. 382, CBS regulation on individuals, read October 16, 2026
- COAD (Receita Federal), CNPJ for individual CBS taxpayers from January 2027, July 2026
- Agência Brasil, government forecasts R$636 billion from the CBS in 2027, August 2026
- DGABC (Broadcast), Receita sends the CBS model to the TCU, September 14, 2026
- Contábeis, CGIBS estimates a 27.91% reference rate, July 2026
- CNB-SP (Ministry of Finance note), the reform and residential rents, January 29, 2026
- Levy Salomão Advogados, updated real estate guide to the reform, March 2026
- Exame, split payment in 2027, September 30, 2026
- Contábeis, split payment rollout will be gradual, July 30, 2026
- Câmara dos Deputados, Lei 15.270/2025 (income tax), November 26, 2025
- Demarest, Receita Q&A on dividends and high incomes, December 2025
- Decreto 9.580/2018 (RIR), art. 763, rent paid to non-residents, read October 16, 2026
- Decreto 9.580/2018 (RIR), art. 781, withholding by the procurador, read October 16, 2026
- Lei 13.259/2016, progressive capital gains rates, read October 16, 2026
- Normas Legais, IN RFB 2.172/2024 (CPF), 2024
- Contábeis, Rio city law 6.250/2017 (ITBI and IPTU), 2017
- TAGD Law, Rio ordered to refund ITBI charged above the sale price, August 2026
- LegisWeb, Rio IPTU 2026, December 2025
- Dizer o Direito, laudêmio and the STJ, December 2022
- STJ, short stays in condominiums need approval (Segunda Seção), May 7, 2026
- STJ, repetitive appeal on short stays in condominiums (Tema 1.443), September 17, 2026
- Lex Legal, Rio city bill on short-stay platforms, April 30, 2026
- FipeZap, residential rent report, September 2026, October 2026
Article texts were read in a consolidated copy of the laws; check the official text on planalto.gov.br. Points marked as open were not settled on October 16, 2026. This guide is general information, not tax or legal advice; your position depends on your residence, structure and other income.
Mais do Journal
 Buying · 2027
Buying property in Rio in 2027
Prices up 5.6% in a year and 13% in Leblon, a stronger real, rates starting to fall, new flights to Galeão: what changes for a foreign buyer in 2027, neighborhood by neighborhood.
 Tributos
Impostos para o proprietário estrangeiro de um apartamento no Rio
Cada imposto brasileiro que um proprietário não residente realmente paga — na compra, durante a posse, sobre a renda de aluguel, na venda e de volta para casa. Sem alarmismo, apenas as alíquotas, os prazos de declaração e os quatro erros a evitar.
 Hosting · Getting paid
Getting paid & staying compliant
The money-flow for a non-resident: the procurador, the flat 15%, DARF and the owner statement, and how the net converts and reaches you abroad. Deduped from the full tax guide, which it links.
Talk to us about your home
Whether you own one apartment or several, we can show you what your statements say about 2027, and introduce you to the accountants and lawyers we work with.